By

October 19, 2026
What Documents Are Required to Open a Business Account in Spain?
Opening a business account in Spain requires companies to provide documentation that confirms their legal registration, ownership structure, business activities, and the identity of the individuals authorized to manage the account.
Whether you operate a Spanish limited company (Sociedad Limitada or SL), a startup, a small or medium-sized enterprise (SME), or a foreign-owned business, preparing the necessary documents in advance can help simplify the application process and reduce delays.
Spanish companies can apply for business accounts through traditional banks and eligible online financial institutions. Many regulated providers offer remote onboarding, allowing businesses to submit their documentation electronically without necessarily visiting a physical branch.
This guide explains what documents are required to open a business account in Spain, why financial institutions request them, and how companies can prepare for a successful application.
The exact documentation required depends on the company's legal structure, ownership, business activities, and the financial institution's compliance requirements.
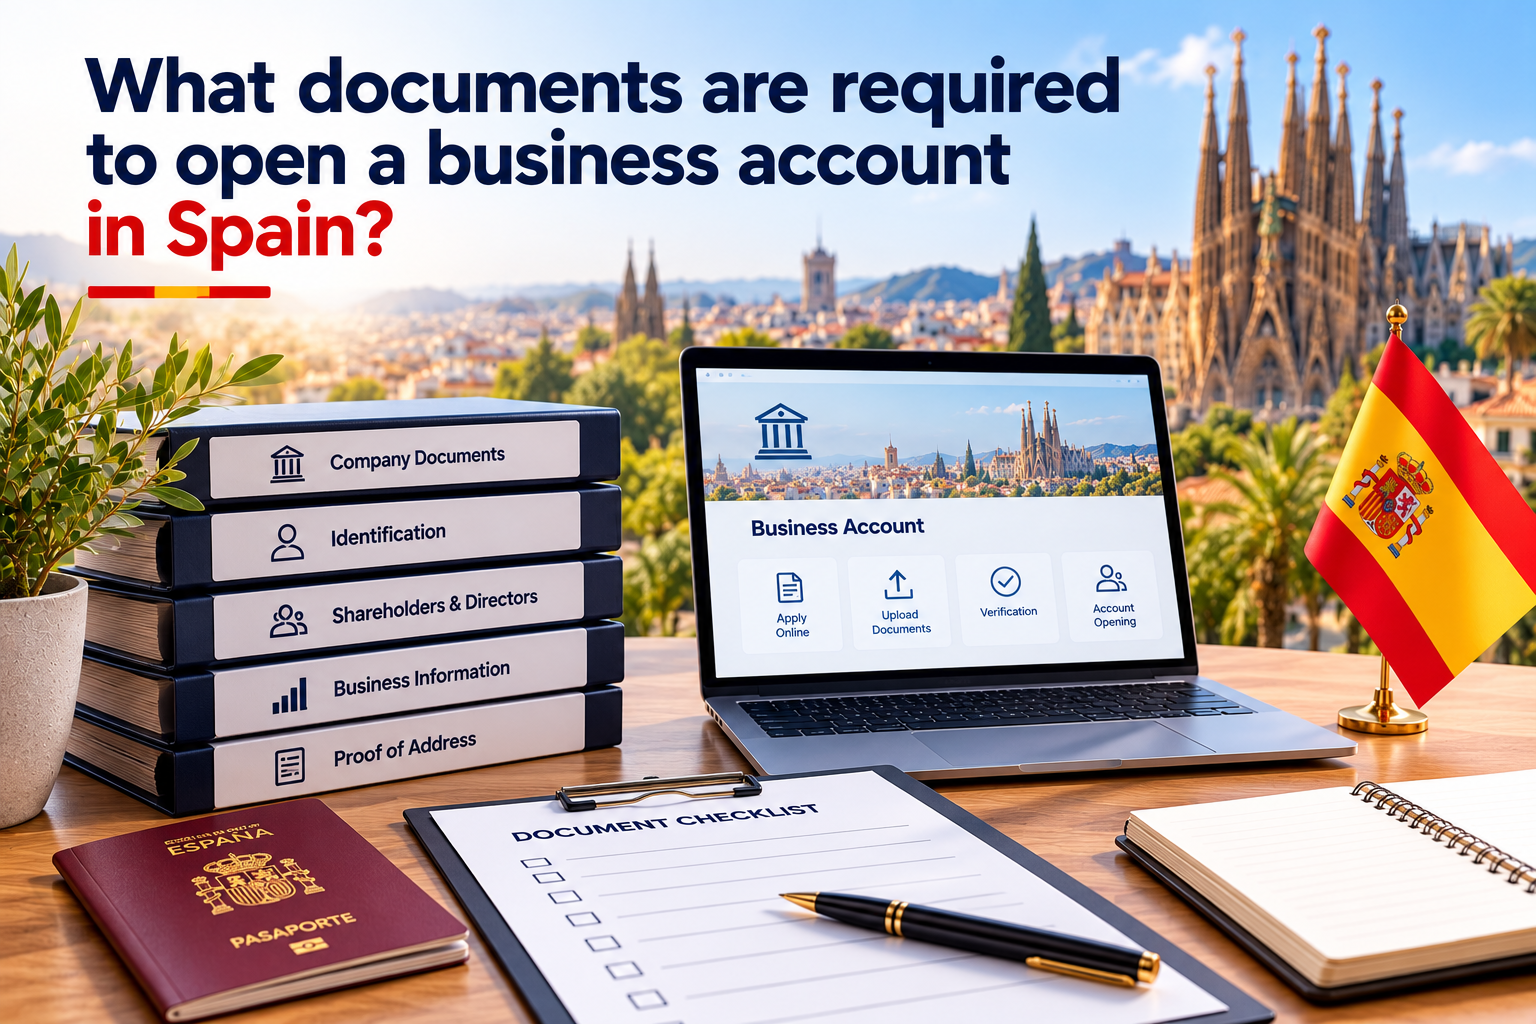
For a Spanish limited company, the following documents are commonly requested:
Not every company will need to submit every document listed above. Additional documentation may be required depending on the business and the provider's assessment.
One of the main requirements for opening a business account in Spain is evidence that the company is legally established.
For companies registered in Spain, financial institutions may request a current extract or certificate from the Spanish Commercial Registry (Registro Mercantil).
This documentation helps confirm important company details, including:
For newly incorporated companies, the financial institution may request incorporation documents and evidence of registration.
Some providers may also verify company information directly through official registries.
Financial institutions may request the company's deed of incorporation, known in Spain as the escritura de constitución.
This document establishes the company's legal formation and may contain information about its shareholders, capital, governance, and administrative structure.
Depending on the company's circumstances, additional constitutional documents or subsequent amendments may also be required.
These documents help financial institutions understand how the company is structured and who has authority to represent it.
Companies registered in Spain generally require a Número de Identificación Fiscal (NIF).
The NIF is used to identify the company for Spanish tax and administrative purposes.
When applying for a business account, companies are normally required to provide their tax identification details.
Newly incorporated companies may initially receive a provisional NIF before obtaining their definitive tax identification documentation.
The account provider will determine which documents are acceptable at each stage of incorporation.
Financial institutions must verify the identities of individuals who represent or control the company.
Directors and authorized representatives may be asked to provide:
For online business account applications, identity verification may be completed electronically.
Some providers may request a photograph, video verification, or other secure identification procedures.
Companies with foreign directors should verify whether the provider accepts their country of residence and identification documents.
Financial institutions are required to identify and verify the individuals who ultimately own or control a company.
These individuals are commonly referred to as Ultimate Beneficial Owners (UBOs).
For Spanish companies, beneficial ownership checks typically consider individuals who directly or indirectly own or control more than 25% of the company, as well as other forms of effective control.
Where no individual can be identified through ownership or control criteria, applicable rules may require identification of relevant senior management.
Financial institutions may request:
Where a company has multiple layers of ownership, additional documents may be required to establish the individuals who ultimately control the business.
Providing accurate beneficial ownership information is an important part of the account opening process.
Financial institutions may request evidence of the company's registered office or principal place of business.
Depending on the provider, acceptable documents may include:
Companies operating from shared offices, serviced offices, or virtual office arrangements may be asked for additional information about their actual business operations.
The documents accepted depend on the financial institution's policies.
A business account provider will generally need to understand the nature of the company's activities.
This is part of the customer due diligence process and helps the institution assess the intended use of the account.
Companies may be asked to explain:
Supporting documentation may include a business website, commercial contracts, invoices, business plans, or other evidence of trading activities.
For newly incorporated companies without a trading history, a clear description of planned operations may be particularly useful.
Financial institutions may request information about the company's expected account activity.
This helps them understand how the account will be used and assess the anticipated payment flows.
Common questions include:
Companies should provide realistic estimates based on their business model and expected commercial activities.
Depending on the company's circumstances, the financial institution may request information about the origin of the funds that will be deposited into the account.
This may include:
Supporting evidence may include financial statements, commercial contracts, invoices, or relevant banking documentation.
New businesses may be asked to explain how their initial operations will be financed.
The level of documentation required depends on the provider's risk assessment and applicable compliance obligations.
Financial institutions must establish which individuals are authorized to open and operate the company's business account.
Depending on the company's management structure, the provider may request:
These documents help confirm that the applicant has the legal authority to act on behalf of the company.
Spanish companies with foreign shareholders or non-resident directors may need to provide additional documentation.
Foreign ownership does not automatically prevent a company from opening a business account. However, more extensive verification may be required for complex or international ownership structures.
Additional documents may include:
Companies with corporate shareholders registered in other countries may need to provide documents tracing ownership to the ultimate individual beneficial owners.
Preparing these documents before applying can help reduce delays.
Yes. Newly incorporated Spanish companies may be eligible to open business accounts even if they have not yet started trading.
The provider may request:
Some providers support companies at an early stage of incorporation, while others require completed registration before opening an operational account.
Businesses should confirm the provider's requirements before applying.
Yes. Many regulated financial institutions allow eligible Spanish companies to upload their documentation through secure online application platforms.
Online onboarding may include:
Depending on the provider and the company's circumstances, the application may be completed remotely.
However, additional verification or original documentation may sometimes be required.
A Spanish company does not necessarily need an IBAN beginning with ES for all its business transactions.
Eligible companies may use European business accounts issued by appropriately regulated financial institutions in other EU countries.
For businesses primarily receiving and sending euro payments, a European IBAN with SEPA payment capabilities can be a practical option.
Under applicable European Union rules, certain forms of IBAN discrimination are prohibited for covered euro credit transfers and direct debits.
However, companies should verify that their account supports their specific operational needs, including tax payments, payroll arrangements, and other administrative requirements.
Spanish companies may open accounts with traditional banks or eligible regulated payment service providers.
Traditional banks may offer services such as deposit accounts, business lending, payment services, and other financial products.
Online payment accounts may focus on electronic payments, euro transfers, digital account management, and related services.
For companies primarily requiring SEPA payments and online account access, a dedicated business payment account may provide suitable functionality.
However, payment accounts provided by electronic money institutions or payment institutions are not necessarily bank deposit accounts.
The applicable safeguarding arrangements and regulatory protections may differ from those available for traditional bank deposits.
Companies should understand these differences before selecting an account.
Proper preparation can help simplify the account opening process.
The company name, registration details, tax identification number, and registered address should be consistent across the submitted documents.
Identification documents should be current, legible, and accepted by the financial institution.
Provide a straightforward description of the company's products, services, customers, and expected transactions.
Make sure the company's ownership structure is transparent and supported by appropriate documentation.
Expected payment volumes should reflect the company's anticipated business activities.
Financial institutions may request clarification or supporting evidence during the compliance review.
Responding promptly can help avoid unnecessary delays.
The main documents commonly include company registration records, incorporation documents, company NIF, director identification, beneficial ownership information, and details of business activities.
Generally, yes. Financial institutions commonly request the company's incorporation deed or other official documents confirming its legal establishment and structure.
Yes. Some providers accept newly established companies without a trading history, although they may request a business plan, expected transaction details, and information about initial funding.
An NIE may be required in certain circumstances, but requirements depend on the provider, the individual's role, and applicable Spanish legal and administrative rules.
Financial institutions commonly verify the company's registered address and may request supporting documentation depending on their compliance procedures.
Yes. Financial institutions generally must identify and verify the individuals who ultimately own or control their corporate customers.
Yes. Many online financial institutions accept electronic document submissions, although additional verification may be required.
Established companies may be asked to provide financial statements or other financial information. Newly incorporated companies may instead provide details of planned activities and expected funding.
Yes. Eligible foreign-owned Spanish companies may apply online, subject to the provider's onboarding requirements and compliance assessment.
Verification times vary depending on the provider, completeness of the documents, company ownership structure, and any additional compliance checks.
Opening a business account in Spain requires companies to provide accurate information about their legal registration, directors, beneficial owners, and business activities.
For Spanish SL companies, startups, SMEs, and foreign-owned businesses, preparing the necessary documents in advance can make the application process more efficient.
Many regulated financial institutions now support online business account applications, allowing eligible companies to submit documentation electronically and complete much of the verification process remotely.
For companies primarily conducting transactions in euros, an online EUR business account with SEPA payment capabilities can provide a convenient way to receive customer payments, pay suppliers, and manage European business transactions.
Looking to Open a Business Account for Your Company in Spain?
Explore online EUR business account solutions for eligible Spanish companies, offering dedicated IBANs, SEPA payment capabilities, and convenient digital account management.
By preparing your company documents and understanding the application requirements, your business can take the next step toward establishing an efficient European payment account.