By

October 20, 2026
What are the requirements for opening a corporate account in Portugal?
Opening a corporate account in Portugal is an important step for companies that need to receive customer payments, pay suppliers, manage business expenses, and conduct financial transactions.
Whether a company is newly incorporated, established, foreign-owned, or managed by non-resident directors, financial institutions must complete identification and compliance procedures before approving a corporate account.
The main requirements generally include valid company registration documents, a Portuguese corporate identification number, identification of directors and shareholders, beneficial ownership information, and details of the company's business activities.
Some banks and authorised payment service providers also allow eligible companies to open corporate accounts online without visiting a physical branch.
For businesses primarily operating in euros, a corporate account offering a dedicated IBAN and Single Euro Payments Area (SEPA) payment capabilities can provide an efficient solution for managing transactions across Portugal and the European Union.
This guide explains the requirements for opening a corporate account in Portugal, the documents needed, the application process, and the considerations for foreign-owned companies and non-resident directors.
Corporate accounts may be available to different types of businesses, subject to the financial institution's eligibility requirements.
These may include:
Not every financial institution accepts every legal structure, industry, or incorporation jurisdiction.
Before applying, companies should confirm that the provider supports their corporate profile and required payment services.
One of the primary requirements for opening a corporate account in Portugal is evidence that the company is legally registered.
Financial institutions must verify the company's legal existence and registration details.
Commonly requested documents include:
The commercial registration certificate helps financial institutions verify the company's legal status and authorised representatives.
For foreign-incorporated companies, equivalent registration documents issued by the relevant foreign authority may be required.
Portuguese companies generally need a corporate identification number, known as the Número de Identificação de Pessoa Coletiva (NIPC).
This number identifies the legal entity and is used for company registration, taxation, and other administrative purposes.
Financial institutions normally request the NIPC when opening a corporate account for a Portuguese company.
The company's NIPC should be consistent across its registration documents and account application.
Foreign companies may be asked to provide their equivalent corporate or tax identification numbers.
Financial institutions must identify the individuals authorised to represent and operate the company's account.
For each relevant director, manager, or authorised representative, the provider may request:
Depending on the institution, proof of residential address may also be required.
Where a director resides outside Portugal, additional identification or verification procedures may apply.
The individual applying for the corporate account must have the legal authority to act on behalf of the business.
Financial institutions may verify this authority through:
For companies requiring joint signatures, the provider may need to verify multiple authorised representatives.
A shareholder is not automatically authorised to operate the company's account simply because they own shares.
The provider must confirm the applicant's authority under the company's legal representation arrangements.
Financial institutions may request information about individuals and companies holding shares or voting rights.
Under the Bank of Portugal's published account-opening identification guidance, relevant corporate identification information includes shareholders and persons with voting rights equal to or greater than 5%.
The provider may request:
Additional information may be required depending on the ownership structure and compliance assessment.
The identification of shareholders should not be confused with the separate requirement to identify ultimate beneficial owners.
Financial institutions must understand who ultimately owns or controls the company.
Portugal maintains the Central Register of Beneficial Owners, known as the Registo Central do Beneficiário Efetivo (RCBE).
The RCBE identifies individuals who ultimately control legal entities through ownership, voting rights, or other arrangements.
For Portuguese companies, beneficial ownership information is generally a mandatory registration requirement.
A person holding more than 25% of a company's capital or voting rights may be an indicator of beneficial ownership, although control can also arise through other means.
The financial institution may request:
Companies with complex ownership structures may need to provide an organisational chart explaining how ownership and control are distributed.
A corporate account application generally requires the company's registered office address.
The financial institution may verify this information using commercial registration documents.
Depending on the circumstances, additional evidence may be requested, such as:
If the company operates from a different location, the provider may also request its principal trading address.
The information submitted should be consistent with the company's official records.
Financial institutions need to understand the nature of the company's commercial operations.
Companies should be prepared to explain:
Depending on the company's activities, supporting information may include:
Newly incorporated companies may provide projected business activities if they do not yet have an established trading history.
Corporate account providers commonly request information about the company's expected financial activity.
This helps the institution understand how the account is likely to be used.
Information may include:
Companies should provide realistic estimates based on their business model.
Where the company is newly incorporated, reasonable projections may be accepted.
Financial institutions may need to understand where the company's funds originate.
Depending on the company's circumstances, supporting documentation may include:
For newly incorporated companies, the institution may ask how the initial business capital was obtained.
For established companies, the provider may review trading history or financial records.
Source-of-funds requirements vary according to the financial institution's assessment of the business relationship.
Portuguese companies generally must register their beneficial ownership information with the RCBE.
The initial declaration is generally required within 30 days following the commercial registration of a newly incorporated company.
Companies must also maintain and update their beneficial ownership information in accordance with applicable rules.
When opening a corporate account, the financial institution may request evidence of RCBE registration or verify the information through available sources.
Incomplete or inconsistent beneficial ownership information can delay the application.
Yes. Foreign-owned Portuguese companies may be eligible to open corporate accounts.
A Portuguese company can generally have foreign individual or corporate shareholders, subject to applicable legal requirements.
However, the financial institution must verify the company's ownership and management structure.
Additional documentation may be required where shareholders reside abroad or where ownership involves foreign companies.
Examples include:
Documents issued abroad may require translation, certification, or authentication.
Foreign ownership does not automatically prevent a company from opening an account, but acceptance depends on the provider.
Yes. A Portuguese company represented by a non-resident director may be eligible to open a corporate account.
The director must have the legal authority to represent the company and satisfy the provider's identification requirements.
The financial institution may request:
Some providers accept remote applications from companies with directors residing outside Portugal.
Others may require additional verification or an in-person appointment.
The director's country of residence may affect eligibility.
Yes. Some banks and authorised payment service providers support online corporate account applications.
Remote onboarding may allow eligible companies to complete the application without visiting a physical branch.
The process may include:
However, fully remote onboarding is not guaranteed for every company.
The provider may require additional documentation or in-person verification.
Not universally.
A Portuguese company may be able to use an eligible business account with an IBAN issued in another European Union country.
Portugal participates in the Single Euro Payments Area (SEPA), which supports standardised euro payments across participating countries.
Under applicable EU rules, eligible SEPA credit transfers and direct debits generally cannot be refused solely because the payment account is located in another EU member state.
However, companies must ensure that the account supports their required payment services and meets applicable Portuguese legal and administrative requirements.
A Portuguese-issued IBAN may offer practical advantages for certain domestic services, but it is not universally required for every business transaction.
Portuguese tax law establishes specific requirements concerning business bank accounts.
Under Article 63-C of Portugal's General Tax Law (Lei Geral Tributária), companies subject to corporate income tax generally must maintain at least one bank account used exclusively for business-related receipts and payments.
The requirement also covers relevant movements involving shareholder loans, advances, and other transactions connected with the company.
This is an important consideration when selecting a corporate account.
Companies should distinguish between traditional bank deposit accounts and accounts provided by payment institutions or electronic money institutions.
Although payment accounts may support euro transfers and business expenses, they are not necessarily legally equivalent to bank deposit accounts.
A Portuguese company intending to rely on a payment or electronic money account as its only corporate account should verify whether it satisfies Article 63-C.
Companies may consider several types of accounts depending on their financial requirements.
These may offer:
Some financial institutions provide digitally managed corporate accounts with online onboarding and payment services.
These may be suitable for companies primarily conducting electronic transactions.
Authorised payment institutions and electronic money institutions may offer payment accounts with:
Companies should understand the differences in account functionality and regulatory protections.
Eligible bank deposits may benefit from deposit guarantee schemes, while payment and electronic money accounts generally operate under different safeguarding arrangements.
A corporate account with SEPA capabilities can support businesses making and receiving euro payments.
Potential benefits include:
Companies can receive eligible euro transfers from customers in participating SEPA countries.
Businesses can make euro payments to suppliers and commercial partners.
Some providers offer business cards for company spending.
SEPA payments can help companies manage euro transactions across European markets.
Digital transaction records can support financial reconciliation and bookkeeping.
Not every provider supports all SEPA schemes, so companies should verify the services available.
There is no universal approval timeframe.
Processing times depend on the financial institution and the complexity of the application.
Some eligible companies may complete onboarding relatively quickly, while others may require several working days or longer.
Factors affecting the timeframe include:
Companies can help reduce avoidable delays by preparing accurate documentation and responding promptly to requests for further information.
Corporate account fees depend on the financial institution and the services required.
Potential charges include:
Some providers may charge separately for physical or virtual business cards.
Businesses should compare the total cost of maintaining and using the account rather than focusing only on the initial opening fee.
Ensure that the provider accepts the company's legal structure, incorporation jurisdiction, ownership arrangements, and business activities.
Prepare the commercial registration certificate, NIPC, and other relevant corporate documents.
Collect the required personal identification and tax information.
Ensure that the ownership structure is clear and that applicable RCBE obligations have been addressed.
Provide a clear description of the company's commercial operations, customers, suppliers, and expected transactions.
Have supporting documents available where required.
Complete the provider's online or branch-based application process.
Follow the institution's procedures for verifying authorised representatives.
Respond to any requests for additional information.
If approved, complete the remaining activation requirements and confirm that the necessary payment services are available.
Applications may be delayed or declined where the financial institution cannot complete its required checks or the company falls outside its eligibility policies.
Common reasons include:
Companies should ensure that the information submitted is accurate and consistent.
Although approval cannot be guaranteed, companies can take practical steps to prepare a stronger application.
Preparation can reduce administrative delays and make the application process more efficient.
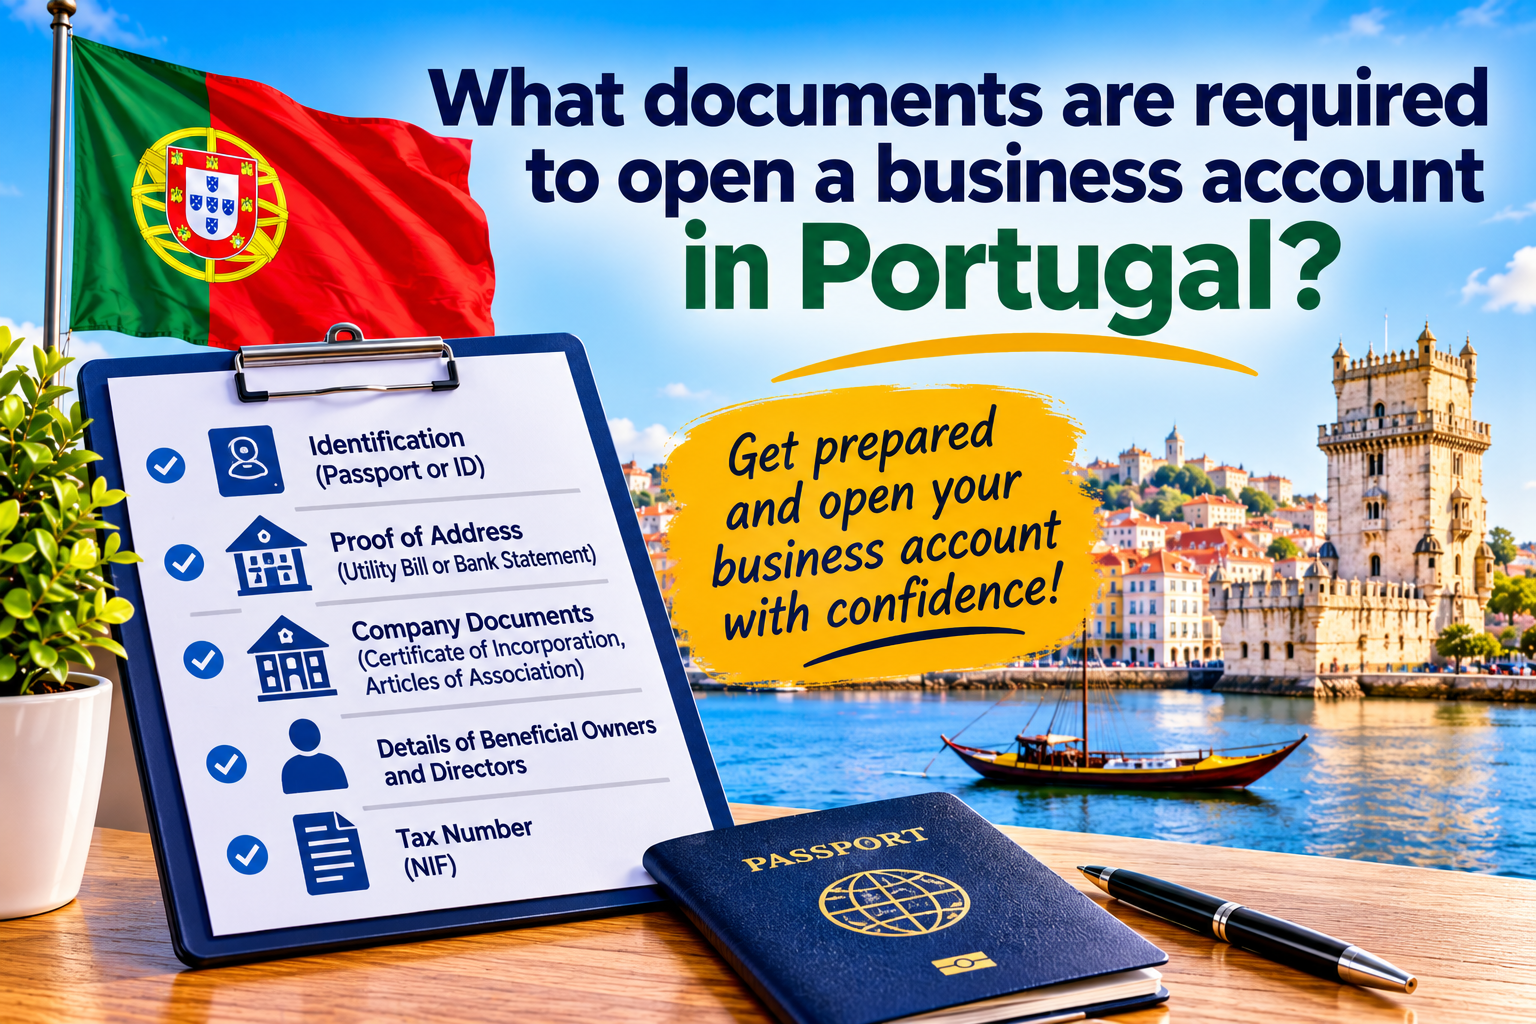
The main requirements generally include company registration documents, a corporate identification number, director identification, evidence of authority, shareholder information, beneficial ownership details, and information about business activities.
Typical documents include a commercial registration certificate, NIPC, incorporation documents, identification of authorised representatives, and beneficial ownership information.
Yes. Portuguese companies are generally required to provide their corporate identification number as part of the account opening process.
Yes. Financial institutions must identify the individuals who ultimately own or control the company. Portuguese companies also have applicable RCBE registration obligations.
Yes. Newly incorporated companies may apply once they have the necessary registration and identification documents.
Yes. Foreign-owned Portuguese companies may be eligible, subject to the provider's compliance and eligibility requirements.
Yes. Some financial institutions accept applications from companies represented by non-resident directors.
Yes. Some providers offer remote onboarding for eligible Portuguese companies.
Not necessarily. Some providers support remote identity verification and online applications.
Not universally. Eligible EU IBANs may generally be used for qualifying SEPA transactions, subject to applicable legal and operational requirements.
Companies subject to corporate income tax generally must maintain at least one bank account dedicated to business activity under Article 63-C of the General Tax Law.
Potentially, yes. However, payment accounts are not necessarily equivalent to bank deposit accounts for every legal purpose.
Processing times vary according to the provider, company structure, documentation, and compliance requirements.
No. Financial institutions independently assess applications and may decline them where eligibility or compliance requirements are not satisfied.
Opening a corporate account in Portugal generally requires the company to provide evidence of its legal registration, identify its directors and authorised representatives, disclose its ownership structure, and explain its business activities.
Financial institutions must also complete applicable customer identification and anti-money laundering checks before approving the account.
Foreign-owned companies, newly incorporated businesses, and companies with non-resident directors may be eligible, although additional documentation or verification may be required.
Some providers offer fully online onboarding, allowing eligible companies to open and manage their accounts without visiting a physical branch.
For Portuguese businesses primarily conducting euro transactions, a suitable corporate account with a dedicated IBAN and SEPA payment capabilities can support customer payments, supplier transfers, and business spending.
However, companies must also comply with Portuguese tax obligations, including the requirement for certain businesses to maintain a dedicated bank account.
By preparing complete documentation, maintaining accurate beneficial ownership records, and selecting a provider that supports their legal structure and payment requirements, companies can make the corporate account opening process more efficient.