By

October 20, 2026
Can I open a business account online in Portugal?
Yes, you can open a business account online in Portugal, provided your company meets the eligibility and verification requirements of the financial institution or payment service provider.
Many businesses prefer online business accounts because they offer convenient access to financial services, digital payment management, and the possibility of applying without visiting a physical branch.
Whether you operate a newly registered Portuguese company, an established business, an e-commerce store, or an international company with commercial activities in Portugal, online business accounts can provide a practical solution for managing day-to-day financial transactions.
Portugal is a member of the European Union and participates in the Single Euro Payments Area (SEPA), allowing eligible businesses to make and receive euro payments across participating European countries.
However, not every financial institution supports fully remote onboarding, and approval depends on the company's legal structure, ownership, business activities, and compliance requirements.
This guide explains how to open a business account online in Portugal, the documents required, the application process, and the benefits for local and foreign-owned companies.
Yes. Some banks and authorised payment service providers offer fully digital account opening procedures for eligible businesses.
Depending on the provider, companies may be able to complete the entire application remotely, including submitting company information, uploading documents, verifying the identity of authorised representatives, and receiving account details.
Online account opening may include:
However, the availability of fully online onboarding varies between institutions.
Some providers may require a video identification procedure, additional documentation, or an in-person appointment.
Companies with complex ownership structures or certain business activities may also face additional verification requirements.
Businesses can choose from different types of financial accounts depending on their operational requirements.
Licensed banks may offer business accounts with online application and management facilities.
Depending on the institution, services may include:
Some banks allow eligible companies to complete the application remotely, while others require in-person identification.
Authorised payment institutions may provide business payment accounts that allow companies to receive and transfer funds electronically.
These accounts may be particularly suitable for businesses primarily requiring euro payments.
Available features may include:
The available services depend on the provider.
Authorised electronic money institutions may offer accounts for holding electronic money and carrying out supported payment transactions.
Although these accounts can provide payment functionality similar to certain bank accounts, they are not necessarily traditional bank deposit accounts.
Businesses should understand the differences in regulatory protection, safeguarding arrangements, and available services before choosing an account.
Eligibility depends on the financial institution's policies and the company's circumstances.
Businesses that may qualify include:
Not every provider accepts every type of business.
Some institutions restrict certain industries, ownership arrangements, or incorporation jurisdictions.
Before applying, companies should confirm that their legal structure and business activities are supported.
Opening an online business account generally involves several stages.
Start by identifying a bank or authorised payment service provider that accepts your company's legal structure and offers the services required.
Important features to consider include:
For companies operating primarily in euros, SEPA payment capabilities may be particularly important.
Before starting the application, verify whether the provider accepts:
Checking eligibility in advance can help avoid unnecessary delays.
Gather the company's registration and identification documents.
Most financial institutions require information confirming the company's legal existence, ownership, management, and activities.
Having these documents ready can make the application process more efficient.
The company representative generally provides details such as:
All information should be accurate and consistent with the company's official registration documents.
The provider may request electronic copies of incorporation documents, identity documents, ownership information, and other supporting records.
Additional documents may be required depending on the company's circumstances.
Financial institutions must verify the identities of customers and relevant company representatives.
Depending on the provider, verification may involve:
Some applications may require additional verification procedures.
The provider assesses the company's information under applicable anti-money laundering and financial compliance requirements.
This may include reviewing the company's business model, ownership structure, expected transactions, and source of funds.
If the application is approved, the company receives instructions for accessing and activating the account.
Depending on the provider, the company may receive a business IBAN, online account access, and the ability to make and receive supported payments.
Approval is not guaranteed, and certain account services may require additional activation steps.
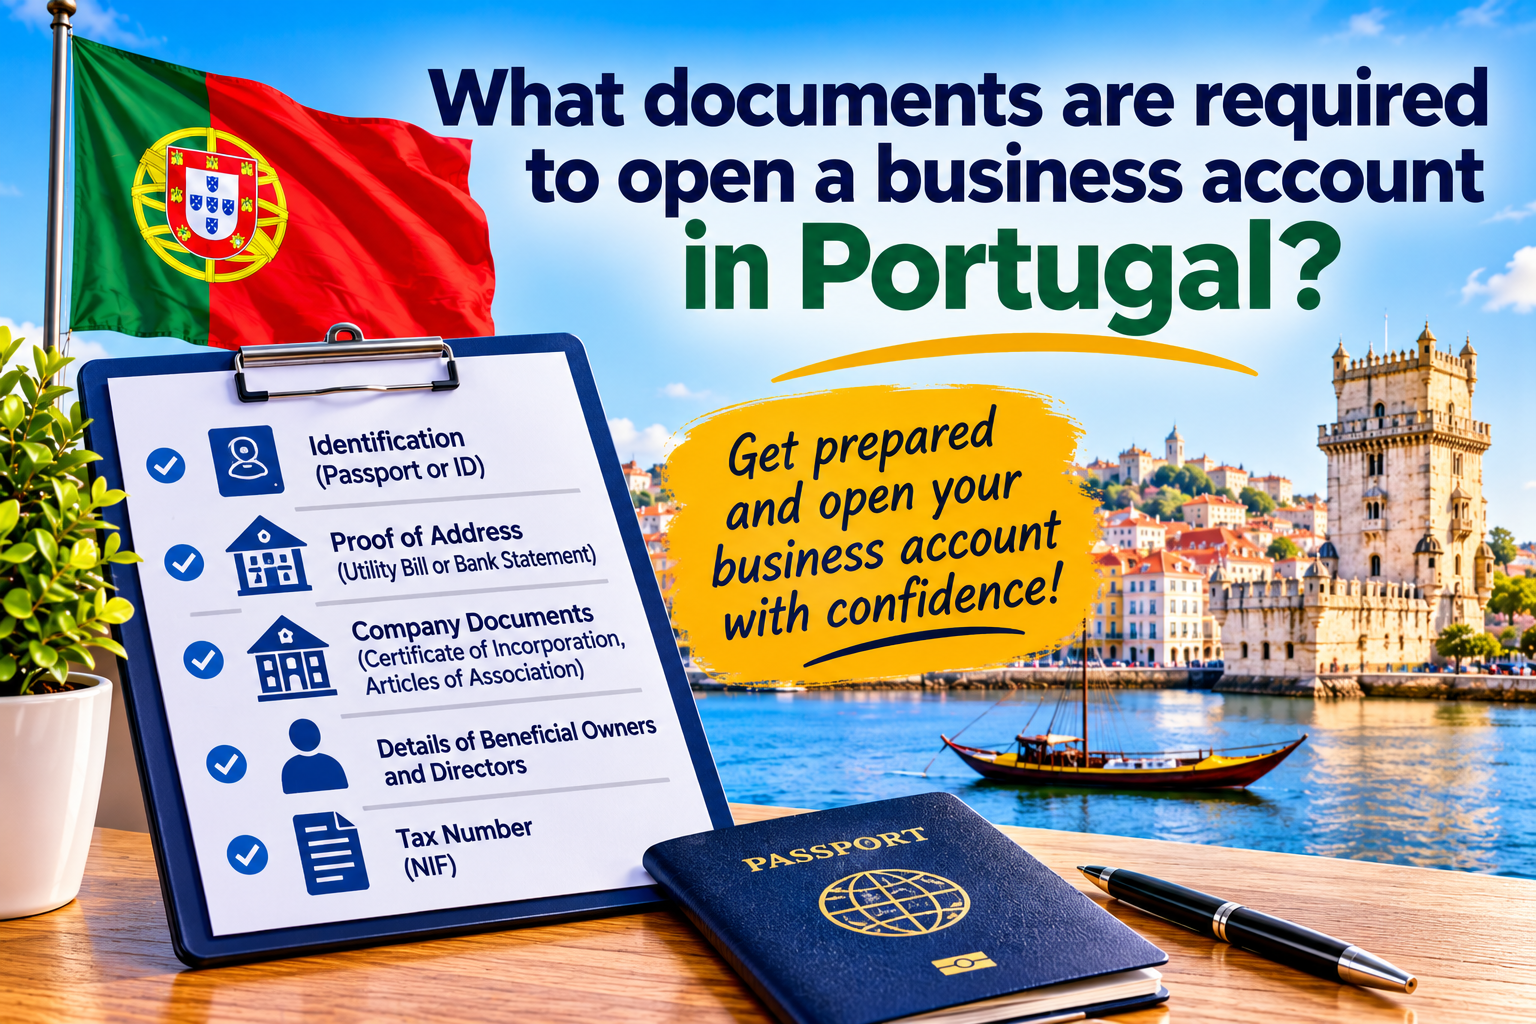
The documents required depend on the financial institution and the company's structure.
Common requirements include the following.
Financial institutions generally require information identifying the individuals who ultimately own or control the company.
For Portuguese companies, information from the Central Register of Beneficial Owners (RCBE) may be relevant.
Providers may request:
Foreign-owned companies may need additional documentation.
Yes. A Portuguese company owned or managed by non-residents may be eligible to open a business account online.
However, the availability of remote onboarding depends on the financial institution.
Some providers accept companies with foreign shareholders or directors, while others impose residency or geographical restrictions.
Non-resident applicants may need to provide:
Additional verification may be required when shareholders or directors live outside Portugal.
Non-resident ownership does not automatically prevent a company from applying, but it does not guarantee acceptance.
Foreign-incorporated companies may be able to apply for business accounts with financial institutions serving Portugal.
However, eligibility depends on the provider and the company's incorporation jurisdiction.
Some institutions accept companies registered in other EU member states, while others only support Portuguese-incorporated businesses.
A foreign company may be asked to provide:
The provider may also request evidence of the company's connection to Portugal.
Businesses should verify whether their incorporation jurisdiction is supported before applying.
A Portuguese company does not necessarily need a Portuguese-issued IBAN for every commercial transaction.
Portugal participates in SEPA, which supports standardised euro payments across participating European countries.
Under applicable EU rules, eligible SEPA credit transfers and direct debits generally cannot be refused solely because the payment account is located in another EU member state.
This is commonly referred to as protection against IBAN discrimination.
A Portuguese company may therefore be able to use an eligible euro payment account with an IBAN issued in another EU country.
However, the account must support the company's required payment services, and certain administrative or operational requirements may need separate consideration.
The suitability of an IBAN depends on the company's financial and commercial needs.
Online business accounts can provide several advantages for entrepreneurs and established companies.
Eligible businesses may be able to apply without visiting a physical branch.
Company representatives can manage payments and review transactions online.
A suitable account can support euro payments to and from participating European countries.
Digital statements and transaction records can support accounting and reconciliation.
Online account management can be useful for companies with foreign directors, shareholders, or commercial partners.
Businesses can review transactions, monitor expenses, and manage supplier payments through supported online services.
Some digital account providers offer pricing structures that may be cost-effective for companies primarily making electronic payments.
Actual costs depend on the provider and the company's transaction activity.
The cost of an online business account varies between financial institutions.
Possible charges include:
Some providers may offer different pricing plans depending on the number of transactions or required services.
Businesses should compare the total expected cost of the account rather than focusing only on monthly fees.
The time required depends on the provider, company structure, documentation, and compliance assessment.
Some eligible businesses may complete the digital application quickly, but account approval may take longer.
Factors influencing processing time include:
Companies with complex ownership arrangements or incomplete documentation may experience longer processing times.
There is no universal approval timeframe applicable to all online business accounts.
Online business accounts can be provided by appropriately authorised financial institutions operating under applicable European financial regulations.
However, businesses should distinguish between different account types.
Eligible deposits held with qualifying banks may be covered by applicable deposit guarantee arrangements, subject to relevant limits and conditions.
Funds held with payment institutions or electronic money institutions are generally subject to safeguarding requirements rather than traditional bank deposit guarantee arrangements.
The legal protections and risks may therefore differ.
Before opening an account, companies should verify the provider's regulatory status and understand how customer funds are held and protected.
Yes. Many online business accounts support SEPA Credit Transfers.
SEPA enables eligible euro payments between accounts in participating countries.
For Portuguese companies, this can help simplify transactions with customers, suppliers, and business partners across Europe.
Depending on the provider, available services may include:
Not all providers offer every SEPA service.
Businesses should verify the supported payment schemes before opening an account.
Some online business account providers offer physical or virtual business debit cards.
These cards may help companies manage operational spending, online purchases, travel expenses, and employee-related payments.
Depending on the provider, available features may include:
Card availability, pricing, and eligibility vary between providers.
Businesses should confirm whether cards are included or subject to additional fees.
Financial institutions may reject or delay applications when they cannot complete the required checks or when a business falls outside their eligibility policies.
Common reasons include:
Providing accurate documentation and a clear description of the company's activities can help reduce avoidable delays.
Yes. Some financial institutions support fully remote applications for eligible businesses. Others may require additional verification or an in-person appointment.
Yes. Newly incorporated companies may apply once they have the required registration and identification documents.
Yes. Foreign-owned Portuguese companies may qualify for online business accounts, subject to the provider's eligibility and compliance requirements.
A company with non-resident shareholders or directors may be eligible. The availability of remote onboarding depends on the provider.
Typical documents include company registration records, a corporate tax identification number, director and shareholder identification, beneficial ownership information, and details of business activities.
Not necessarily. Eligible euro payment accounts issued in other EU member states can generally be used for qualifying SEPA payments, subject to applicable requirements.
Some providers support international payments. The available countries, currencies, and payment methods depend on the account.
Application and approval times vary. Some providers offer streamlined digital onboarding, while more complex applications may require additional verification.
Yes, provided the account supports the relevant SEPA payment services.
Yes. Online accounts can be useful for e-commerce businesses that need digital account management, euro transfers, and transaction records. Separate merchant payment processing services may be required for card acceptance.
Some providers offer virtual and physical business cards, depending on account eligibility and available services.
Not necessarily. Payment accounts and bank deposit accounts may differ in their services, legal structure, and customer fund protection arrangements.
Yes. Eligible companies can open business accounts online in Portugal through banks and authorised payment service providers that support digital onboarding.
Online business accounts can provide convenient financial management, access to SEPA payments, a dedicated business IBAN, and the ability to manage transactions remotely.
They can be particularly useful for startups, small businesses, e-commerce companies, and international businesses conducting euro-denominated transactions.
Portuguese companies with foreign shareholders or non-resident directors may also qualify, although additional documentation and compliance checks may apply.
Before applying, businesses should compare account features, fees, eligibility requirements, payment capabilities, and regulatory protections.
By selecting a suitable provider and preparing the necessary documentation, entrepreneurs can establish an efficient payment account to support their business activities in Portugal and across Europe.