By

October 20, 2026
How to open a business account in Portugal?
Opening a business account in Portugal is an important step for entrepreneurs, startups, small businesses, and international companies operating in the Portuguese market. A dedicated business account helps companies manage financial transactions, receive customer payments, pay suppliers, and maintain clear financial records.
Whether you are establishing a new company in Portugal, operating an existing Portuguese business, or expanding your international operations, choosing the right business account can help support efficient financial management.
Portugal is a member of the European Union and participates in the Single Euro Payments Area (SEPA), making it a suitable location for companies conducting euro transactions with customers and suppliers across Europe.
Businesses can explore account options offered by banks and authorised payment service providers, depending on their operational needs, ownership structure, and eligibility.
This guide explains how to open a business account in Portugal, the documents required, the application process, and the considerations for Portuguese companies and foreign business owners.
A business account provides a dedicated financial facility for managing company transactions separately from personal finances.
For companies operating in Portugal, this can help simplify accounting, payment processing, and financial administration.
The main benefits include:
A suitable business account can also provide access to online payment management, transaction reporting, and other financial services.
The specific features depend on the account provider.
Before opening a business account, it is important to understand the different types of providers and account services available.
Business accounts offered by licensed banks may provide services such as deposits, transfers, debit cards, payment facilities, and other banking products.
The available features depend on the institution and the type of business.
Some financial institutions offer business accounts that can be applied for and managed online.
These accounts may provide digital onboarding, online transfers, transaction monitoring, and electronic statements.
Online business accounts can be particularly convenient for entrepreneurs who manage their businesses remotely.
Authorised payment institutions and electronic money institutions may offer business payment accounts designed for receiving, holding, and transferring funds.
Depending on the provider, these accounts may include a dedicated IBAN and access to SEPA payments.
However, payment accounts are not necessarily the same as traditional bank deposit accounts.
The applicable safeguarding arrangements, deposit protection, account functionality, and regulatory treatment may differ.
Businesses should understand the type of financial institution and account they are using before applying.
Business account eligibility depends on the financial institution's policies, regulatory requirements, and the company's circumstances.
Commonly assessed factors include:
Portuguese limited liability companies, sole traders, partnerships, branches, and other eligible business structures may be able to apply for business accounts.
Foreign-owned Portuguese companies may also qualify, although additional documentation or verification may be required.
Account approval is not automatic.
Financial institutions must verify the identity of their customers and understand the nature of their business relationships.
For this reason, companies are generally required to provide documents supporting their legal existence, ownership, management, and commercial activities.
The exact documentation varies by provider.
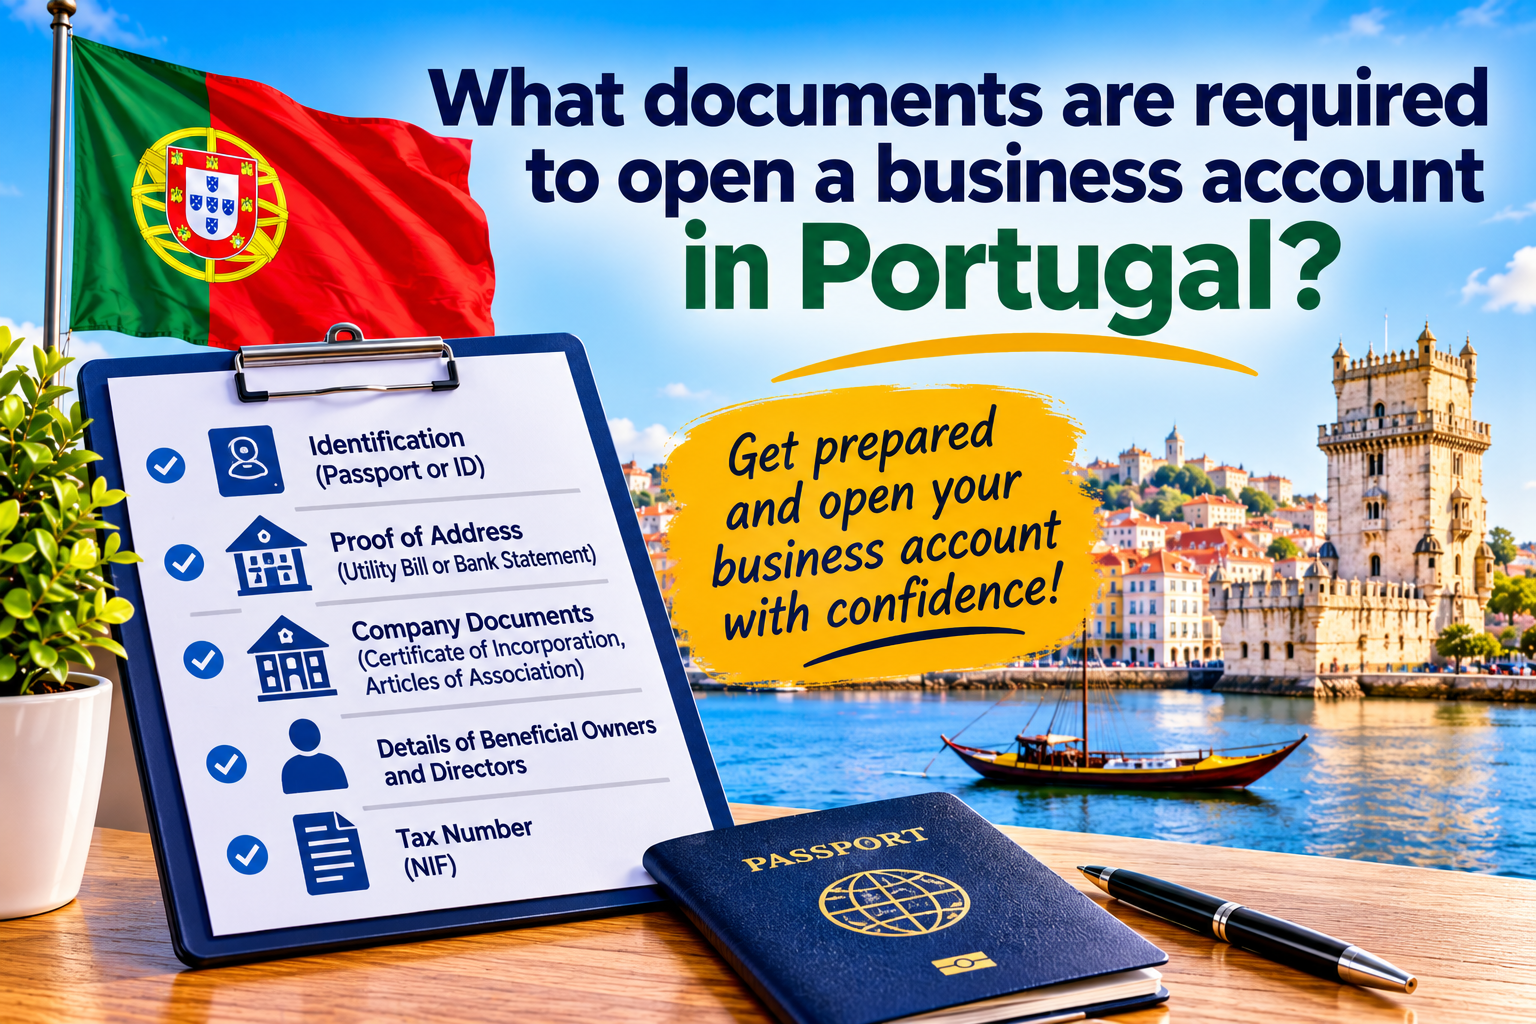
A Portuguese company may be asked to provide:
Financial institutions may request:
Businesses may need to provide information identifying the individuals who ultimately own or control the company.
For Portuguese companies, information concerning the Central Register of Beneficial Owners (Registo Central do Beneficiário Efetivo, or RCBE) may be relevant.
Depending on the company's circumstances, the provider may request:
Companies with foreign shareholders or directors may be asked to provide additional identification, ownership, or corporate documentation.
Documents issued abroad may need certified translations or authentication.
Preparing the required documents in advance can help reduce delays during onboarding.
Selecting a suitable account provider is an important part of establishing financial operations in Portugal.
Businesses should compare account features based on their actual payment and operational requirements.
Important considerations include:
SEPA Payments
Check whether the account supports sending and receiving SEPA Credit Transfers.
Business IBAN
Determine whether the account provides a dedicated IBAN and whether its country of issuance meets the company's operational requirements.
Online Account Management
Consider whether the account can be accessed and managed remotely.
Fees and Charges
Review monthly account fees, transaction charges, card fees, and any applicable international payment costs.
Foreign Ownership Eligibility
Confirm whether the provider accepts companies with non-resident directors or shareholders.
Payment Limits
Review transaction limits and any restrictions relevant to the business.
Additional Services
Determine whether the company requires debit cards, direct debits, bulk payments, or other financial services.
The best business account is not necessarily the one with the lowest fees. It should provide the services required for the company's commercial activities.
Once the company has selected a suitable provider, it can begin the application process.
Depending on the institution, applications may be submitted online or through a physical branch.
The application commonly requires information about:
The company may also need to identify the individuals authorised to operate the account.
Providing complete and accurate information can help the provider assess the application more efficiently.
Financial institutions operating in Portugal must comply with applicable anti-money laundering and counter-terrorist financing requirements.
These obligations include identifying customers, understanding ownership structures, and assessing the purpose of business relationships.
The verification process may involve:
Some providers support remote identity verification, while others may require in-person procedures.
Companies with complex ownership arrangements or international activities may undergo more extensive checks.
If the application is approved, the provider will provide the relevant account details and instructions for activation.
Depending on the account, the company may receive:
Some providers may require an initial deposit or additional verification before all services become available.
Businesses should review the account terms, payment limits, fees, and operating conditions before using the account.
Yes. Some financial institutions allow eligible businesses to apply for business accounts online.
Digital onboarding may allow company representatives to submit information, upload documents, complete identity verification, and receive account approval remotely.
Online business account applications may offer advantages such as:
However, not every Portuguese company or ownership structure will qualify for fully remote onboarding.
The provider may require additional documentation or in-person verification.
A non-resident may be able to open a business account for a Portuguese company, depending on the financial institution's eligibility requirements.
Portuguese companies can generally have foreign shareholders and directors, subject to applicable corporate and regulatory rules.
Financial institutions may nevertheless apply additional verification procedures when the company is owned or managed by individuals living abroad.
These may include:
Non-resident ownership does not automatically prevent a company from applying for a business account, but approval remains subject to the provider's assessment.
Foreign companies may be able to open business accounts with providers serving Portugal, depending on eligibility and the nature of their activities.
Some institutions accept businesses incorporated in other EU countries, while others may have more restrictive requirements.
A foreign company may be asked to provide:
Additional documents may be necessary for companies incorporated outside the European Union.
Not every account provider accepts foreign-incorporated businesses.
A Portuguese company does not necessarily need a Portuguese-issued IBAN for every commercial payment.
Portugal participates in SEPA, which supports standardised euro payments across participating countries.
Under applicable EU rules, eligible SEPA credit transfers and direct debits generally cannot be refused solely because the payment account's IBAN was issued in another EU member state.
This principle is commonly referred to as IBAN discrimination protection.
For example, a Portuguese company may be able to use an eligible euro payment account with an IBAN issued in another EU country for its commercial transactions.
However, businesses should ensure that the account supports their required services and complies with any applicable legal or administrative requirements.
A Portuguese IBAN may still be preferred for certain operational reasons, but it is not universally required for all business payments.
The Single Euro Payments Area is a framework designed to make euro payments across participating European countries more consistent and efficient.
Portugal's participation in SEPA allows eligible businesses to make and receive euro payments using supported payment services.
For Portuguese businesses trading with customers and suppliers across Europe, SEPA payment capabilities can be an important feature of a business account.
The time required to open a business account in Portugal varies depending on the provider, the company's structure, and the completeness of the submitted documentation.
Some eligible businesses may complete digital onboarding relatively quickly, while others may require several working days or longer.
Factors affecting the application process include:
There is no universal approval timeframe applicable to every business account provider.
Companies should prepare the required documents before applying and respond promptly to requests for additional information.
Business account fees vary between financial institutions and account types.
Potential charges may include:
Some providers may offer different pricing structures depending on transaction volumes and required services.
Businesses should review the full fee schedule before selecting an account.
A low monthly fee does not necessarily mean the account will be the most cost-effective option for a company making frequent payments.
The account arrangements required during company formation depend on the legal structure and incorporation procedure.
For Portuguese companies with share capital, the applicable capital contribution and deposit requirements must be considered.
Certain company formation procedures permit capital contributions to be completed within prescribed periods rather than requiring a traditional bank deposit before incorporation.
A business account may therefore be needed at a different stage depending on the circumstances.
Regardless of the incorporation procedure, having an appropriate business account is generally important for managing the company's ongoing financial transactions.
Entrepreneurs should verify the applicable capital and account requirements before registering their company.
A dedicated business account can support a company's financial organisation and day-to-day operations.
Maintaining separate financial records helps distinguish company transactions from personal expenses.
A dedicated account provides transaction records that can support bookkeeping, reconciliation, and financial reporting.
Businesses can receive customer payments through supported bank transfer and payment services.
Companies can use their accounts to pay suppliers, employees, and other commercial obligations.
A suitable account can support euro payments through SEPA.
Online account management and transaction records can help business owners monitor income, expenses, and cash flow.
Applications may be delayed when financial institutions require additional information or cannot complete the necessary verification procedures.
Common issues include:
Providing clear, accurate, and consistent information can help make the application process more efficient.
Yes. Some financial institutions offer online applications for eligible Portuguese companies. Remote onboarding availability depends on the provider and the company's circumstances.
Common requirements include company registration documents, a corporate tax identification number, director and shareholder identification, beneficial ownership details, and information about business activities.
Yes. Foreign individuals who own or manage Portuguese companies may be able to open business accounts, subject to the financial institution's eligibility and compliance requirements.
A company with a non-resident director may be eligible to open a business account. The provider may request additional identification and verification documents.
Yes. Newly incorporated Portuguese companies can generally apply for business accounts once they have the necessary registration and identification documentation.
Not necessarily. Eligible SEPA payment accounts issued in other EU countries can generally be used for qualifying euro transfers and direct debits, subject to applicable requirements.
Approval times vary depending on the provider, company structure, documentation, and verification requirements. Some applications may be processed quickly, while more complex cases may take longer.
Yes. A Portuguese company with a suitable payment account can receive SEPA Credit Transfers from participating countries.
Some providers support remote onboarding for eligible businesses, although additional verification or in-person procedures may be required.
Some authorised financial institutions and payment service providers offer eligible foreign companies business payment accounts with IBANs. Availability depends on incorporation jurisdiction, business activities, and compliance requirements.
Safety depends on the provider's regulatory status, security arrangements, and account structure. Businesses should verify whether the provider is appropriately authorised and understand whether funds are held as bank deposits or safeguarded under payment or electronic money regulations.
Important factors include eligibility, SEPA payment capabilities, fees, online access, transaction limits, account features, regulatory protections, and customer support.
Opening a business account in Portugal involves selecting a suitable financial institution, preparing the required company documents, completing identity and beneficial ownership verification, and obtaining account approval.
Portuguese companies can explore business accounts offered by banks and authorised payment service providers, including options that support online onboarding and euro payments.
For businesses trading with customers and suppliers across Europe, access to SEPA payments and a dedicated business IBAN can help simplify financial operations.
Foreign-owned and non-resident-managed companies may also be eligible for business accounts, although additional verification requirements may apply.
The most suitable account will depend on the company's legal structure, ownership, transaction requirements, and long-term business objectives.
By preparing accurate documentation, understanding the available payment services, and comparing account features carefully, entrepreneurs can establish an appropriate financial foundation for operating and growing a business in Portugal.