By

October 20, 2026
Can a non-resident director open a Portuguese business account?
Yes, a non-resident director can generally apply to open a business account on behalf of a Portuguese company, provided they have the legal authority to represent the company and meet the financial institution's identification and compliance requirements.
Portugal allows companies to appoint directors and managers who live outside the country, subject to applicable corporate and regulatory requirements. This makes Portugal an option for international entrepreneurs, foreign investors, and business owners who wish to establish or manage a Portuguese company without relocating.
However, opening a business account as a non-resident director is not always as straightforward as applying as a Portuguese resident.
Banks and authorised payment service providers must verify the company's legal registration, ownership structure, business activities, and the identity of individuals authorised to operate the account.
Some financial institutions offer online business account applications and remote identity verification, while others may require additional documentation or an in-person appointment.
This guide explains how non-resident directors can open business accounts for Portuguese companies, the documents required, remote application options, and the benefits of using a business account with euro SEPA payment capabilities.
Yes. Portuguese companies can generally appoint directors or managers who reside outside Portugal.
For example, a Portuguese private limited liability company, known as a Sociedade por Quotas (Lda.), may appoint an eligible individual living in another EU country or outside the European Union as its manager.
Portuguese corporate law does not impose a universal Portuguese residency requirement on every company director or manager.
However, certain circumstances may involve additional requirements relating to tax registration, representation, regulated activities, or the company's effective management.
It is also important to distinguish between owning a Portuguese company, serving as its director, and having authority to operate its financial accounts.
A non-resident director must have the appropriate legal authority to act on behalf of the company when applying for a business account.
Yes. A Portuguese company represented by a non-resident director may be eligible to open a business account with a bank or authorised payment service provider.
The financial institution will generally assess:
Non-residency does not automatically prevent a company from opening an account.
However, financial institutions may apply different onboarding policies and may not accept every country of residence or ownership arrangement.
Account approval is subject to the provider's eligibility and compliance assessment.
Not necessarily.
A Portuguese company may be able to open a business account even if its director lives abroad.
Some financial institutions accept applications from companies with non-resident directors, particularly where the company has a clear ownership structure and provides complete documentation.
However, a provider may require additional verification when the director is not physically present in Portugal.
This may include:
The availability of remote onboarding depends on the financial institution.
A Portuguese residential address is not universally required for a director, but the company must provide accurate information about the director's actual residence.
The documentation required depends on the financial institution and the company's circumstances.
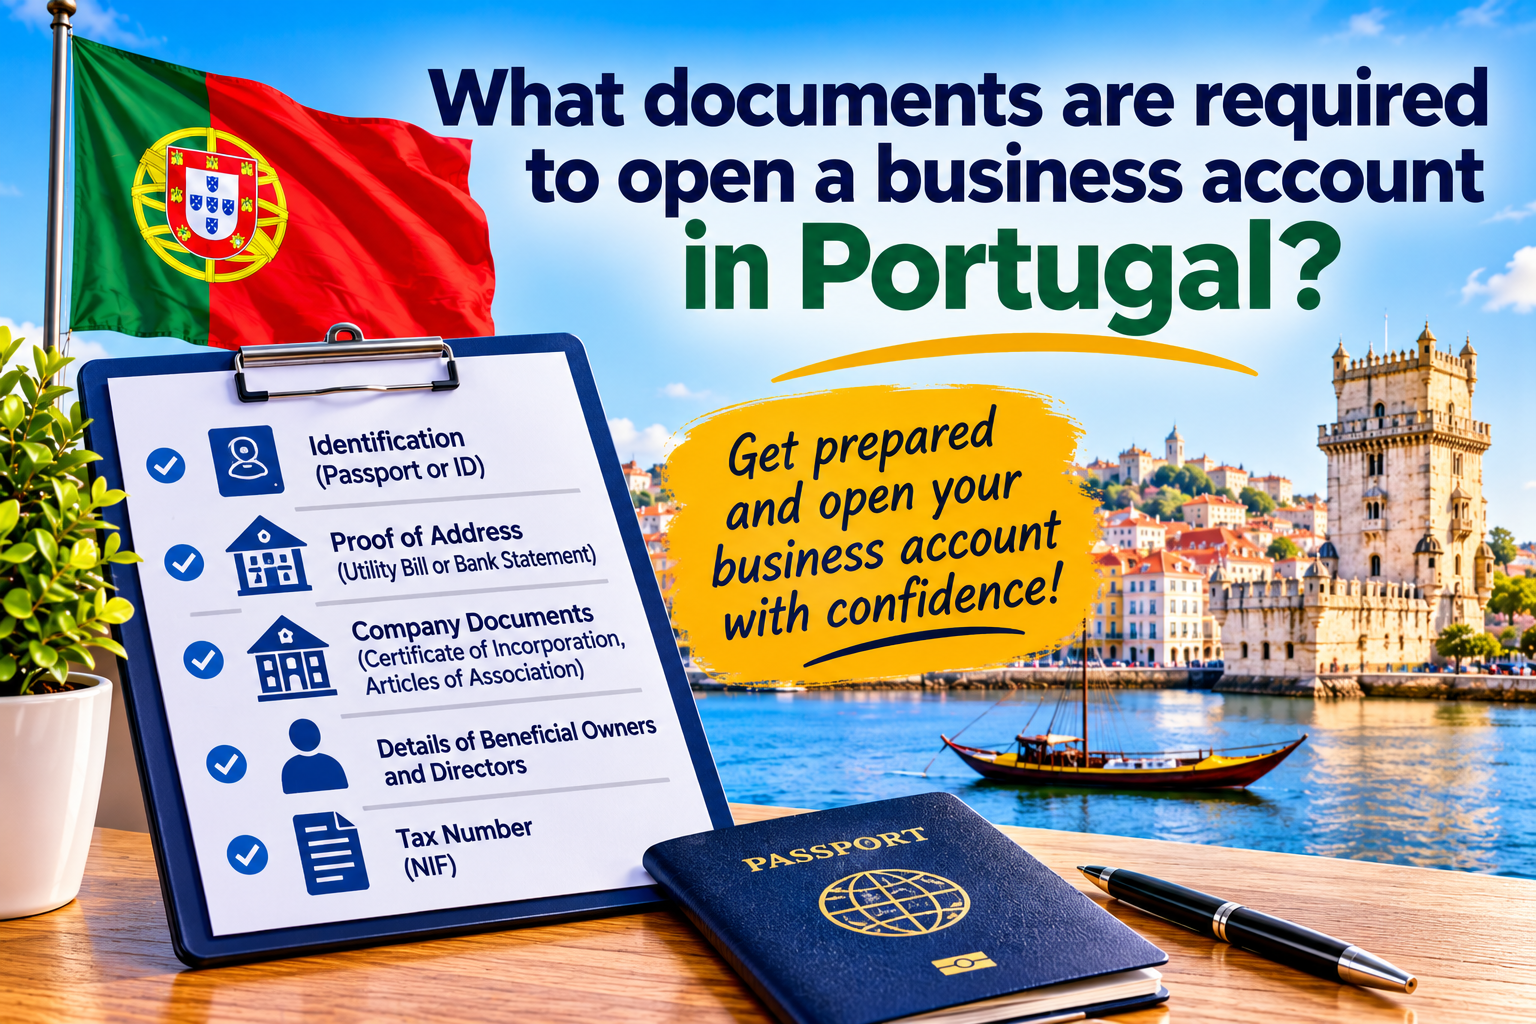
The following documents and information are commonly requested.
The director may need to provide a valid passport or national identity card.
The financial institution uses this information to verify the individual's identity.
The director may be asked to provide a Portuguese tax identification number (NIF) and, where relevant, foreign tax identification information.
Portuguese tax registration requirements depend on the individual's role and circumstances.
A financial institution may also request tax residency information for regulatory and reporting purposes.
The provider may request evidence of the director's residential address.
Acceptable documents vary but may include:
The provider may specify how recently the document must have been issued.
The institution must establish that the director is authorised to act on behalf of the Portuguese company.
This may be confirmed through:
Some providers may require video identification, electronic identity verification, or certified documentation.
These procedures help financial institutions comply with applicable customer identification requirements.
In addition to the director's personal information, the Portuguese company generally needs to provide documents confirming its legal existence and ownership structure.
Common requirements include:
For Portuguese companies, information from the Central Register of Beneficial Owners (Registo Central do Beneficiário Efetivo, or RCBE) may be required.
Companies with foreign corporate shareholders may need to provide additional documents explaining their ownership structure.
Yes. Some banks and authorised payment service providers support online business account applications for companies represented by non-resident directors.
Digital onboarding may allow an authorised representative to complete the application without travelling to Portugal.
Depending on the provider, the process may involve:
However, fully remote onboarding is not available for every company or director.
Some providers may require an in-person appointment or additional verification procedures.
Before applying, it is advisable to confirm whether the provider accepts directors residing in the relevant country.
Potentially, yes.
A Portuguese company represented by a director living outside the European Union may be eligible to open a business account.
However, non-EU residency may result in additional compliance checks or eligibility restrictions.
Financial institutions may consider:
Some providers may accept directors from certain non-EU jurisdictions but not others.
The company's Portuguese registration does not automatically guarantee acceptance.
In many circumstances, yes.
A foreign director who legally represents a Portuguese company does not necessarily need a Portuguese residence permit solely to apply for a business account.
A person can serve as a company director while residing abroad, subject to applicable legal requirements.
However, the financial institution may request identification, tax information, and evidence of the director's country of residence.
If the director intends to live or work physically in Portugal, separate immigration and residence requirements may apply.
Opening a business account does not itself grant the director immigration or residence rights.
A Portuguese tax identification number, known as the Número de Identificação Fiscal (NIF), is commonly relevant when an individual holds a formal role in a Portuguese company.
Whether a particular director must obtain a Portuguese NIF, appoint a tax representative, or complete other tax registration procedures depends on their circumstances and applicable Portuguese tax rules.
Financial institutions may request the director's NIF as part of the account application.
Non-resident directors should clarify their Portuguese tax registration obligations before applying.
The company's corporate identification number (NIPC) is separate from the director's personal tax identification number.
Yes. A Portuguese company may be able to use an eligible euro business payment account with an IBAN issued in another EU member state.
Portugal participates in the Single Euro Payments Area (SEPA), which supports standardised euro payments across participating countries.
Under applicable EU rules, eligible SEPA credit transfers and direct debits generally cannot be refused solely because the payment account is located in another EU member state.
This protection is commonly referred to as the prohibition of IBAN discrimination.
A Portuguese-issued IBAN is therefore not universally necessary for every business payment.
However, the account must support the company's required services, and any applicable administrative or operational requirements must be considered.
For a Portuguese company managed from abroad, an online account with SEPA payment capabilities may offer convenient access to euro transactions.
Online business accounts can provide several advantages for Portuguese companies managed by directors living abroad.
Authorised representatives may be able to access account information and manage payments without visiting Portugal.
A suitable account can support euro transfers to and from customers and suppliers in participating countries.
Businesses can manage payments to commercial partners through supported online services.
Some providers offer physical or virtual business cards for operational spending.
Online statements and transaction histories can support bookkeeping and financial reporting.
Remote access can help directors oversee payment activity from another country.
The specific features depend on the account provider.
The application process generally involves the following steps.
Ensure that you are legally authorised to represent the Portuguese company.
Your authority should be reflected in the relevant company records or supported by appropriate corporate documentation.
Select a bank or authorised payment service provider that accepts Portuguese companies with non-resident directors.
Confirm whether your country of residence is supported.
Gather the company's commercial registration records, NIPC, incorporation documents, and beneficial ownership information.
Have your passport or identity card, tax identification details, and proof of address available where required.
Provide a clear description of the company's products or services, customers, suppliers, and expected transactions.
Complete the application online or through the institution's designated procedure.
Follow the provider's instructions for identity checks, document submission, and any additional compliance requirements.
If the application is approved, complete the remaining activation steps and obtain access to the account.
Processing times vary between financial institutions.
Some eligible companies may complete digital onboarding relatively quickly, while others may require several working days or longer.
Applications involving non-resident directors may take additional time where foreign documents or further identity checks are required.
Factors affecting processing time include:
There is no universal guaranteed approval timeframe.
Preparing complete documentation can help reduce avoidable delays.
Business account fees depend on the financial institution and the services required.
Potential charges include:
Businesses should compare the total cost of account operation rather than focusing only on the monthly maintenance fee.
The director's non-resident status does not necessarily mean that the account will have higher fees, although provider-specific pricing and eligibility conditions may apply.
Opening a Portuguese business account while living abroad may involve additional administrative requirements.
Not every financial institution supports fully remote onboarding.
Some documents may require certification, translation, or authentication.
The provider may require evidence of the director's actual residential address abroad.
Companies with multiple foreign shareholders may need to provide additional beneficial ownership information.
Financial institutions may request supporting documents explaining the company's commercial operations.
Some institutions may not accept directors residing in certain jurisdictions.
Understanding these requirements before applying can help avoid unnecessary delays.
Yes. A Portuguese company represented by a non-resident director may be eligible to open a business account, subject to the provider's requirements.
Not necessarily. Some providers accept companies managed by directors residing abroad.
Yes. Some financial institutions support online applications and remote identity verification for eligible companies.
Potentially, yes. Eligibility depends on the financial institution, the director's country of residence, and applicable compliance requirements.
Not necessarily for the purpose of applying for a company business account. Separate immigration requirements may apply if the director intends to live or work in Portugal.
A Portuguese NIF may be required in connection with the director's corporate role or tax obligations. The specific requirements depend on the individual's circumstances.
Common requirements include valid identification, tax identification information, residential address details, and evidence of authority to represent the company.
Yes. Eligible euro payment accounts issued in other EU member states can generally be used for qualifying SEPA transactions, subject to applicable requirements.
Some account providers offer physical or virtual business cards to eligible companies and authorised users.
Processing times vary depending on the provider, company structure, documentation, and verification requirements.
Yes. Newly registered companies may apply once they have the necessary incorporation, identification, and ownership documentation.
No. Financial institutions assess applications individually and may decline them if eligibility or compliance requirements are not satisfied.
Yes. A non-resident director can generally apply for a business account on behalf of a Portuguese company, provided they are authorised to represent the business and meet the financial institution's requirements.
The director does not necessarily need to live in Portugal or hold a Portuguese residence permit solely to apply for the company's account.
However, the financial institution must verify the director's identity, the company's registration, its beneficial owners, and its commercial activities.
Some providers support fully online onboarding, allowing eligible Portuguese companies to apply and manage their accounts remotely.
For companies operating primarily in euros, a suitable business account offering a dedicated IBAN and SEPA payment capabilities can help simplify transactions with customers and suppliers across Europe.
By preparing accurate documentation and choosing a provider that accepts non-resident directors, Portuguese companies can improve the efficiency of the application process and establish the payment services needed for their business operations.